
Key Takeaways
- US equities saw mixed trading on Monday, October 12, 2026, with the S&P 500 maintaining proximity to its all-time high as energy gains offset tech underperformance.
- Brent crude prices jumped 2% to $106.77 per barrel, driven by geopolitical tensions, escalating inflation fears ahead of critical CPI and PPI reports this week.
- The Federal Reserve’s 2% inflation target remains distant, with market participants anticipating further rate hikes and scrutinizing corporate earnings for validation of AI-driven growth.
New York, October 12, 2026 Wall Street commenced the week with mixed trading that kept the broader market near its recent record peaks, as a surge in oil prices boosted energy stocks while tech giants weighed on indices. The S&P 500 advanced a modest 0.1%, clinging to the record level established last week. The Dow Jones Industrial Average added 228 points, or 0.4%, by midday Eastern time, while the Nasdaq composite edged down 0.2%.
Investors are closely monitoring a packed week of economic data and corporate earnings, with inflation figures and the performance of major banks set to dictate market direction. The persistent uncertainty surrounding crude oil supplies and the Federal Reserve’s interest rate trajectory continue to inject daily volatility into equity markets.
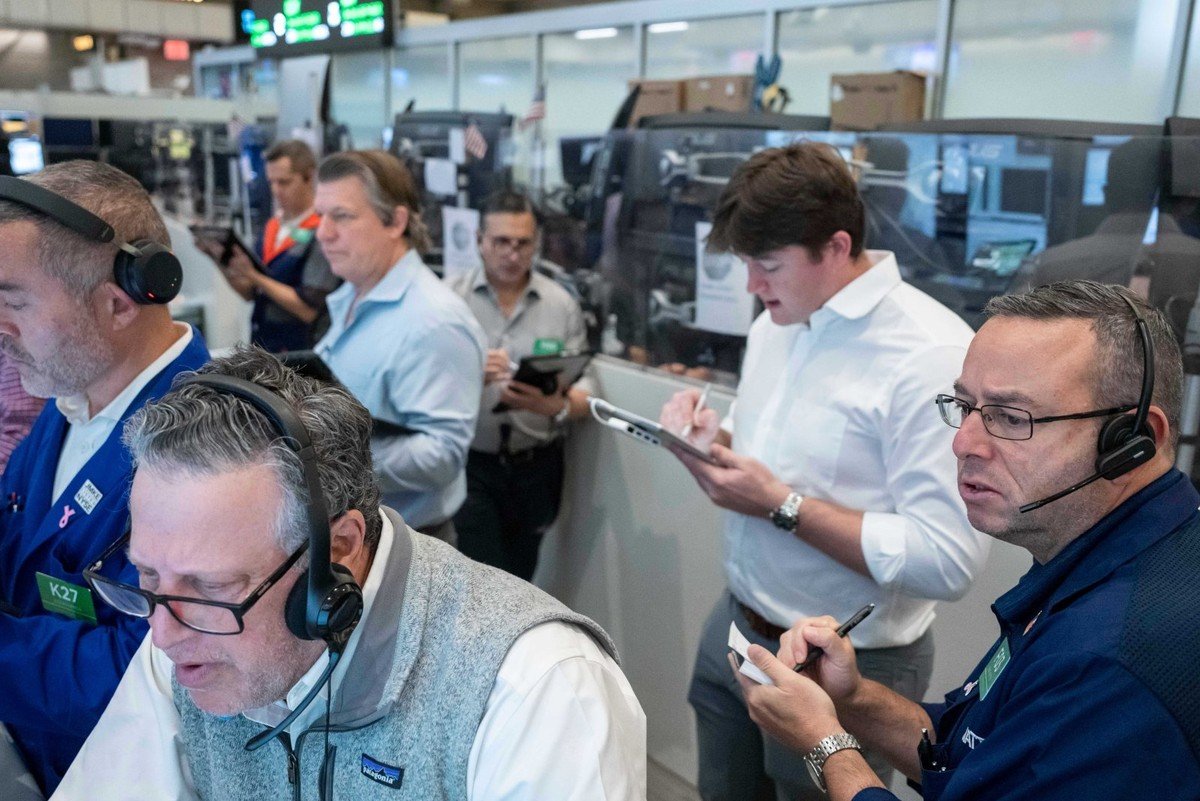
Photo: Options traders Marty Handler (foreground) and Matt Hefter (right) on the floor of the New York Stock Exchange, Oct. 8, 2026. (AP Photo/Yuki Iwamura)
US Stocks Hold Near Records: What’s Driving the Volatility?
Despite the S&P 500 hovering around its all-time high, Monday’s trading reflected underlying market tensions. The energy sector posted some of the day’s strongest gains, with Chevron rising 1.4% as Brent crude, the international benchmark, jumped 2% to $106.77 per barrel. This rise in crude prices, oscillating between $96 and nearly $110 over the past month, is largely attributed to continued uncertainty surrounding the U.S. war with Iran and its implications for global energy supplies.
Conversely, technology stocks acted as the primary drag on the market. Micron Technology declined 2.8%, and Advanced Micro Devices fell 2.4%. These firms, with their substantial market capitalizations, exert significant influence on the broader indices. While they have been the key drivers behind the year’s record market gains, analysts are now scrutinizing their ability to translate the artificial intelligence frenzy into tangible future earnings growth.
Inflation Threat Mounts: CPI, PPI, and the Fed’s Next Move
The surge in energy prices directly contributes to inflationary pressures across the economy. Higher crude costs translate to elevated gasoline prices for consumers and increased diesel costs for freight, impacting everything from food to consumer goods. This week’s economic calendar includes critical inflation updates that Wall Street will dissect.
On Wednesday, the U.S. government will release the Consumer Price Index (CPI) for September, which economists expect to show an acceleration to 3.6% from 3.4% in August. The Producer Price Index (PPI), measuring inflation at the business level, is due Thursday and is also anticipated to remain stubbornly high. Both figures sit well above the Federal Reserve’s long-term 2% target rate, reinforcing expectations for another interest rate hike before year-end. The 10-year Treasury yield, which closed at 5.24% late Friday, reflecting bond market reactions to inflation and rate hike expectations, remained closed Monday for the Columbus Day holiday.
Oil Price Swings and Geopolitical Risks: Impact on Global Markets
The persistent volatility in oil prices is deeply tied to geopolitical developments. The ongoing U.S. conflict with Iran remains a significant supply-side risk. Adding to the complexity, President Donald Trump’s social media announcement last Friday detailed a deal to purchase Russian diesel from President Vladimir Putin. This move, aimed at tempering rising fuel prices ahead of the November 3 U.S. midterm elections, directly contradicts U.S. efforts to curtail Russia’s oil and gas revenue that funds its war against Ukraine, creating a conflicted policy landscape that could further destabilize energy markets.
Analyst Perspective & Market Impact
Magdalena Ocampo, market strategist at Principal Asset Management, noted in a recent report that AI continues to support growth, reinforcing the outlook for tech and critical suppliers across the supply chain. Yet uncertainty about AIs long-term impact persists, making future gains more reliant on earnings delivery rather than potential. From FiniPots vantage, the market’s current hovering near record highs is a precarious balance. The divergence between ambitious AI narratives and the impending reality of tech sector earnings, coupled with inflation persistently fueled by volatile energy prices, creates a challenging investment environment. Bond yields reflect this tension, signaling investor caution even amidst equity market strength.
| Market Index/Commodity | Daily Change (Oct 12, 2026) | Current Level/Context |
|---|---|---|
| S&P 500 | +0.1% | Trading near all-time high |
| Dow Jones Industrial Average | +0.4% (228 points) | N/A |
| Nasdaq Composite | -0.2% | N/A |
| Brent Crude | +2% | $106.77 per barrel |
| 10-year Treasury Yield | N/A (Bond market closed) | 5.24% (Late Friday close) |
With major banks reporting earnings this week against a backdrop of rising interest rates, can corporate profits sufficiently underpin current market valuations, or will persistent inflation and geopolitical energy shocks finally trigger a broader market pullback?
Leave a Reply