
Key Takeaways
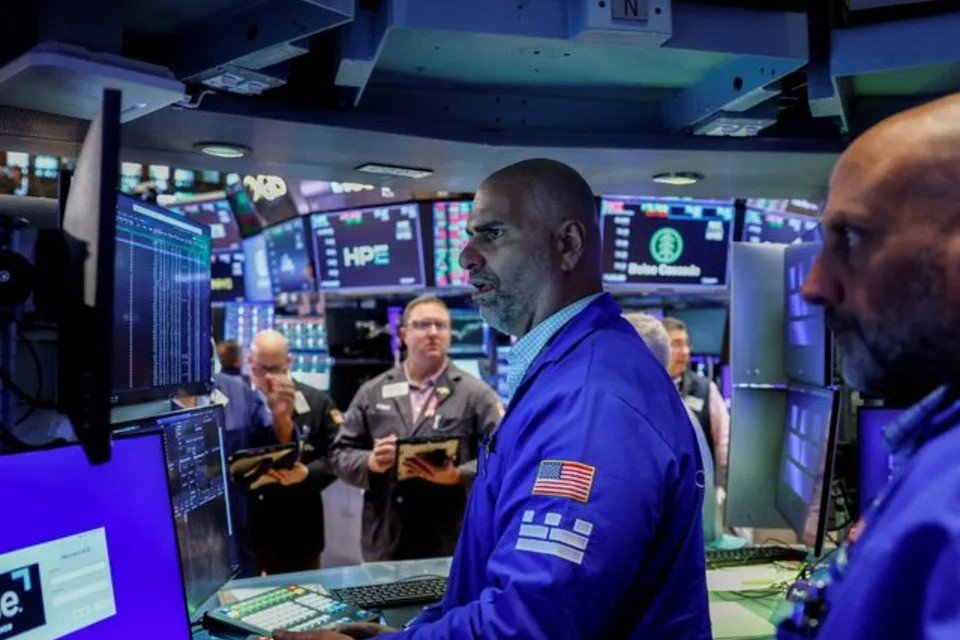
- Wall Street indices closed higher on Friday, September 25, 2026, propelled by investor optimism in AI and hopes for de-escalation in the Middle East.
- Microsoft shares surged 3.3% after unveiling new Copilot AI capabilities, leading gains in the heavyweight technology sector.
- Probability of a Federal Reserve rate hike in October increased to 66.4%, reflecting persistent inflation concerns driven by geopolitical conflicts and government debt.
Wall Street’s main indices saw modest gains on Friday, September 25, 2026, as enthusiasm around artificial intelligence innovation and cautious optimism regarding Middle East peace negotiations buoyed investor sentiment. Microsoft (MSFT) shares advanced 3.3%, providing the largest boost to the S&P 500, following the software giant’s announcement of several new features for its Copilot application, including a coding tool and an always-on AI agent.
What Drove Wall Street’s AI Rally?
The technology sector emerged as the week’s best performer, climbing 0.8% on Friday and offsetting declines across seven of the 11 S&P 500 sectors. Beyond Microsoft’s Copilot enhancements, chipmaker Qualcomm gained 5.1%, while Nvidia was marginally higher and Dell advanced 5%. Further fueling AI-related optimism, Meta’s Muse and its integrated device, Charm, reportedly gained traction among younger consumers. This traction follows significant capital expenditure in AI technology, a trend noted by Jamie Cox, managing partner at Harris Financial Group. "The amount of money being deployed into the economy from AI investment is just so strong, and we haven’t even seen the productivity piece of it," Cox stated, suggesting this underpins market valuations and limits significant sell-offs. Separately, Akamai Technologies surged 7.3% on news of an $11.6 billion cloud services agreement with leading AI firm Anthropic.
How Are Global Geopolitics & Inflation Impacting Markets?
Market sentiment also received a lift from reports indicating US and Iranian negotiators continued discussions on a phased resolution to the Middle East conflict. This potential path involves Tehran reopening the Strait of Hormuz in exchange for Washington lifting its economic blockade. However, broader optimism was constrained by ongoing inflation concerns, largely stemming from the prolonged conflicts in Iran and Ukraine, coupled with rising government debt levels. Brent crude oil, while easing slightly on the day, remained above $100 a barrel, contributing to inflationary pressures. Concurrently, the yield on the 10-year Treasury note stood at 5.2%. Geopolitical discussions extended to a meeting between President Donald Trump and President Xi Jinping, where Trump conveyed US concerns regarding Chinese support for Iran.
What Does the FedWatch Tool Signal for October Rates?
Against this backdrop of inflation worries, traders increased their expectations for the Federal Reserve to raise interest rates. The CME Group’s FedWatch Tool now indicates a 66.4% probability of the Fed increasing rates by at least 25 basis points in October, a notable rise from approximately 50% earlier in the week. Remarks from Federal Reserve policymakers, including John Williams and Beth Hammack, are anticipated later in the day, potentially offering further insight into the central bank’s stance.
Analyst Perspective & Market Impact
Jamie Cox of Harris Financial Group highlights the sheer volume of capital flowing into AI infrastructure as a powerful economic force. This significant investment is not yet fully reflected in productivity gains but is already baked into market valuations, creating a floor against major corrections. However, this tech-driven buoyancy faces a strong countercurrent from persistent inflation, high energy prices, and rising Treasury yields, which amplify the pressure on the Federal Reserve to maintain a hawkish stance. The market’s increasing expectation for an October rate hike indicates that macro concerns, particularly inflation fueled by geopolitical instability, remain a critical factor influencing investor decisions despite AI enthusiasm.
| Index/Company | Friday’s Close | Daily Change |
|---|---|---|
| Dow Jones Industrial Average (DJIA) | 51,526.74 | +0.34% |
| S&P 500 (^GSPC) | 7,718.15 | +0.18% |
| Nasdaq Composite | 26,997.07 | +0.21% |
| Microsoft (MSFT) | – | +3.31% |
| Qualcomm (QCOM) | – | +5.1% |
| Nvidia (NVDA) | – | -0.04% |
| Dell (DELL) | – | +5.0% |
| Meta (META) | – | -3.2% |
Will the momentum from substantial AI investment and potential geopolitical de-escalation be sufficient to counteract the persistent inflation and rising interest rate expectations that continue to pressure global markets?
Leave a Reply