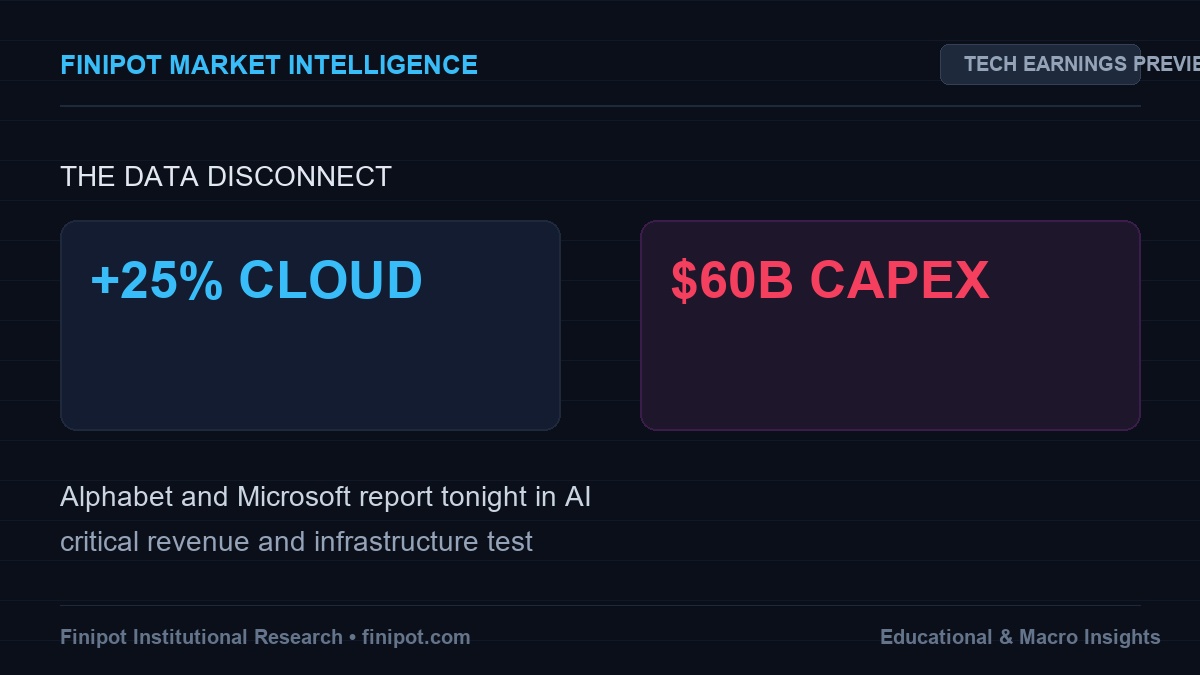
- Alphabet (GOOGL): Consensus Revenue: ~$86.4 Billion | Cloud Revenue Growth Expected: ~25.2%
- Microsoft (MSFT): Consensus Revenue: ~$64.5 Billion | Azure Revenue Growth Target: 29% – 31%
- Combined Annualized AI Capex: Surpassing $62 Billion across servers, power, and chips
- Key Metric: “AI Revenue Run Rate” — how much incremental revenue is generated directly by generative models
The Moment of Truth for the AI Supercycle
Following weeks of nervous range-bound trading, Wall Street stands on the precipice of its most critical reporting cycle of 2026. After the closing bell on Wednesday, October 28, Alphabet Inc. (NASDAQ: GOOGL) and Microsoft Corporation (NASDAQ: MSFT) will release third-quarter financial results, providing definitive proof of whether corporate adoption of artificial intelligence is translating into bottom-line cash flow.
For the past four quarters, investors rewarded tech megacaps simply for announcing aggressive infrastructure roadmaps and partnership agreements. Tonight, that tolerance has ended. Institutional asset managers are demanding concrete evidence that multi-billion-dollar capex lines spent on Nvidia clusters, liquid cooling systems, and specialized LLM inference engines are driving accelerating revenue growth.
Alphabet: Google Cloud Margin Expansion & Search Defensibility
Alphabet enters the session looking to demonstrate that its Google Cloud Platform (GCP) can maintain its 25%+ trajectory while expanding operating margins past 11%. Key focal points for Sundar Pichai’s team include:
- AI Search Overviews Monetization: Demonstrating that AI-driven search results are not cannibalizing high-margin commercial text ads.
- Custom Silicon (TPU v6): Proving that in-house Tensor Processing Units are reducing external GPU procurement costs and boosting cloud margins.
Microsoft: Azure Capacity Constraints vs. Enterprise Demand
For Microsoft, the spotlight falls squarely on Azure. Investors will scrutinize whether previously reported data center power constraints have eased sufficiently to allow Azure AI to sustain growth above 30%. With Copilot licenses rolling through enterprise renewals, CFO Amy Hood’s forward guidance for fiscal Q2 will dictate trading direction across global semiconductor and software equities.
Disclaimer: This financial overview is for analytical and informational purposes only. Do not trade options or equities based solely on earnings previews.
Leave a Reply