
Key Takeaways
- Applied Digital (APLD) reported fiscal Q1 2027 revenue of $341.9 million, a 322% year-over-year surge, significantly exceeding analyst estimates of $116.3 million.
- The robust growth stemmed primarily from its high-performance computing hosting segment, particularly $183.5 million in tenant fit-out services for AI data center buildouts.
- Despite strong revenue and $3.7 billion in cash and equivalents, the company disclosed $6.4 billion in total debt, presenting a substantial financial balancing act for its rapid expansion.
Applied Digital (APLD) reported its fiscal first-quarter 2027 earnings on Wednesday, October 7, surpassing revenue expectations as its aggressive buildout of AI data centers began converting into significant income streams. The Houston-based data center operator posted revenue of $341.9 million for the quarter ended August 31, a dramatic 322% increase from the prior year period. This figure far outstripped the $116.3 million revenue analysts had projected, according to Barron’s, sending Applied Digital shares up 3.8% ahead of Thursday’s market open.
While revenue surged, the company posted an adjusted loss of one cent per share for the quarter, outperforming expectations for a 29-cent adjusted loss. On a GAAP basis, net loss attributable to common stockholders from continuing operations widened to $221 million, or $0.76 per share, compared to a net loss of $18.5 million, or $0.07 per share, in the same period a year earlier. Adjusted EBITDA, however, saw a substantial rise to $64.4 million from $0.5 million in the fiscal first quarter of 2026.
Applied Digital Q1 2027 Report: What Drove the Revenue Beat?
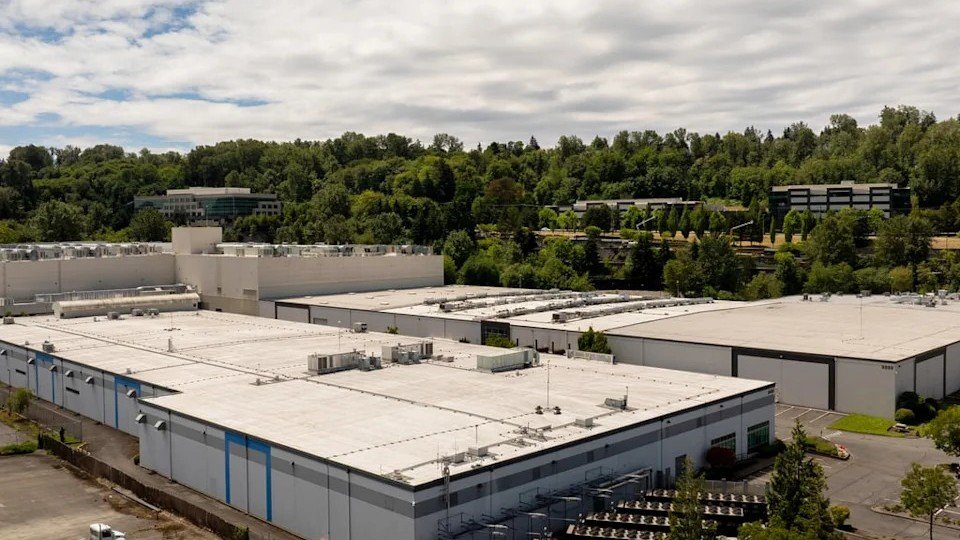
The core of Applied Digital’s revenue expansion came from its high-performance computing (HPC) hosting business, which generated $262.6 million. This included $183.5 million from tenant fit-out services, reflecting substantial investment by clients in custom AI infrastructure, and $65.8 million in base rental revenue. The companys data center hosting segment, which caters to crypto mining customers, contributed $37.8 million during the quarter.
CEO Wes Cummins underscored the company’s ambition, stating, “Our goal is to establish Applied Digital as the category leader in the design, construction, deployment, and operation of purpose-built AI factories.” He emphasized a long-term vision focused on developing large-scale, sustainable AI factory campuses and securing durable, high-quality, long-term contracts with tier-one, investment-grade hyperscalers.
Applied Digital’s Balance Sheet: Cash, Debt, and Future Capacity
As of the quarter’s close, Applied Digital held approximately $3.7 billion in cash, cash equivalents, and restricted cash. This liquidity is contrasted by a total debt load of approximately $6.4 billion. The financial structure highlights the capital-intensive nature of building out next-generation AI infrastructure, a sector where U.S. data-center construction spending surpassed $50 billion in April for the first time, according to Census Bureau figures.
Subsequent to the quarter’s end, Applied Digital continued its expansion. On October 1, it delivered the second 75-megawatt phase of Building 2 at its Polaris Forge 1 campus, bringing total live capacity there to 250 MW. The company also announced securing up to approximately 1 gigawatt of potential power capacity in Finland and entering a power purchase agreement with Base Electron for energy from a natural gas-fired generation facility slated for development in North Dakota.
The company reported leases for approximately 1.41 GW of critical IT load across five campuses as of August 31, representing approximately $36 billion of contracted revenue over their initial base terms. This includes a 15-year lease valued at $7.5 billion signed in April with an undisclosed U.S.-based hyperscaler at its Delta Forge 1 campus, adding a second investment-grade customer to its portfolio.
Applied Digital’s Long-Term AI Vision and Hyperscaler Strategy
Applied Digital’s strategy is squarely aimed at capturing the growing demand for AI computing power. The firm’s focus on securing long-term contracts with major hyperscalers, coupled with its aggressive build-out of purpose-built AI factory campuses, positions it within a high-growth segment of the technology sector. The shift towards providing specialized infrastructure for AI, rather than solely crypto mining, reflects a broader industry trend towards more diversified and robust revenue streams.
Analyst Perspective & Market Impact
Applied Digital’s Q1 results paint a picture of impressive top-line growth driven by a strategic pivot into high-value AI infrastructure. The significant beat on revenue, alongside an adjusted loss narrower than expected, will likely reassure investors about the company’s operational execution in scaling its AI data center capacity. The $36 billion in contracted revenue over initial terms highlights substantial long-term demand and revenue visibility. However, the balance sheet demands scrutiny: the $6.4 billion debt load, significantly outweighing cash reserves, poses a material financing risk, particularly in a higher interest rate environment. While growth is robust, the cost of capital and the ability to service this debt could impact future profitability and expansion plans. Analysts will be closely watching the company’s capital allocation and debt reduction strategies in upcoming quarters.
| Category | Description |
|---|---|
| Strengths | Explosive Q1 revenue growth (+322% YoY) driven by AI, $36B long-term contracted revenue, strategic focus on tier-one hyperscalers, expanding power capacity. |
| Weaknesses | Substantial $6.4 billion total debt, widening GAAP net loss ($221M), capital-intensive business model, reliance on potentially lumpy tenant fit-out revenue. |
| Opportunities | Continued robust demand for AI infrastructure, securing additional investment-grade hyperscaler contracts, geographic expansion (Finland), potential for scale efficiencies. |
| Threats | High interest rates impacting debt servicing costs, intense competition from established data center operators, potential slowdowns in AI capital expenditure, execution risks in large-scale construction. |
With Applied Digital demonstrating impressive revenue acceleration in AI infrastructure, can the company successfully manage its $6.4 billion debt load while continuing its aggressive expansion, or will financing costs weigh heavily on future profitability and shareholder returns?
Leave a Reply