
Key Takeaways
- GameStop reported an adjusted EPS of $0.17 and a $44.8 million net profit, marking a significant return to profitability.
- CEO Ryan Cohen and several company directors used personal funds to acquire additional GME shares on the open market.
- Operational improvements, including stronger collectibles sales, contrast with a wide range of fair value estimates, from $30 to $420.69.
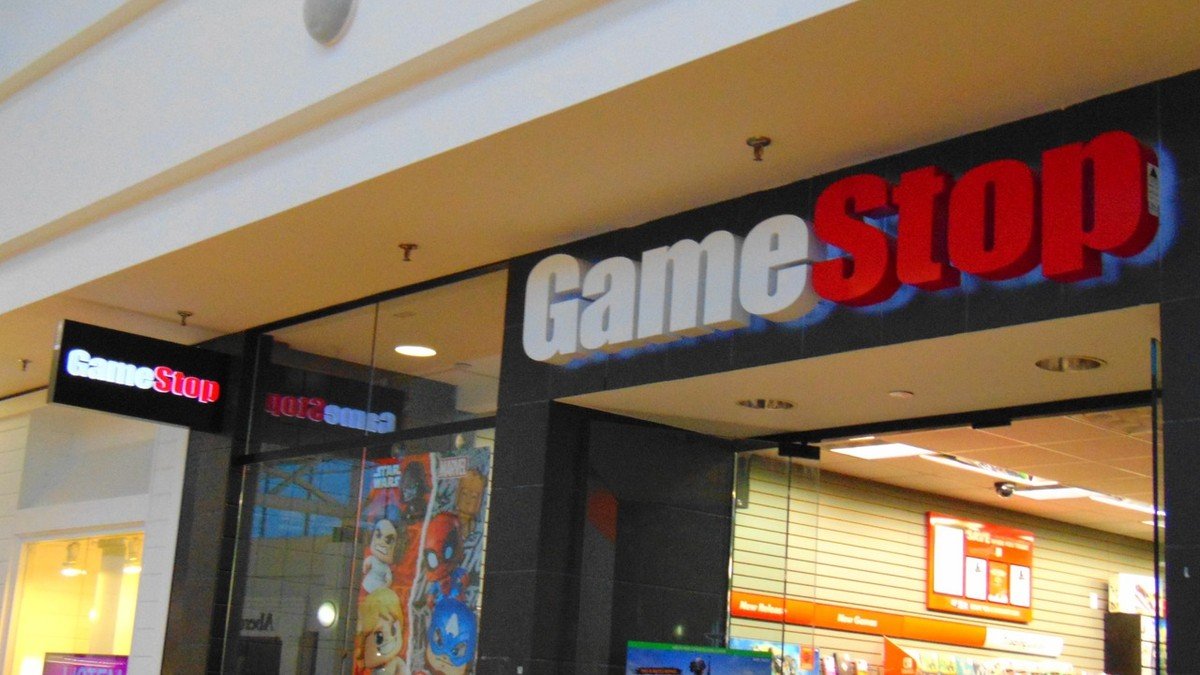
GameStop Corp. (NYSE: GME) recently reported a significant financial shift, posting an adjusted earnings per share (EPS) of $0.17 and a net profit of $44.8 million. This development signals a return to profitability for the specialty retailer, supported by higher operating income and robust sales within its collectibles segment. The operational news gains additional context from open market purchases of GME shares by CEO Ryan Cohen, who acquired a million shares, alongside buys from several other directors. These actions highlight leadership’s personal conviction in the company’s ongoing turnaround strategy.
What is driving GameStop’s return to profitability?
GameStop’s recent profit print stemmed from a combination of tighter operations, a leaner cost base, and a growing collectibles business. The company’s strategy includes reducing inventory and controlling store costs effectively, avoiding heavy capital spending that could erode progress. The higher operating income reflects these efficiencies. Stronger collectibles sales have also contributed meaningfully, demonstrating an ability to carry some of the load as physical game demand may soften. For sustained positive earnings, GameStop must maintain these operational disciplines and ensure consumer appetite remains consistent for its evolving product mix.
How significant is the insider buying at GameStop?
The open market share purchases by CEO Ryan Cohen and other directors add a layer of conviction to GameStop’s investment narrative. Ryan Cohen’s million-share purchase, funded with personal capital, reinforces the idea that leadership stands behind the strategic roadmap, even as the stock price experiences daily volatility. Historically, insider buying at these levels can be viewed by investors as a strong signal of belief in future performance, aligning management’s interests directly with shareholders. This action sharpens attention on the execution of GameStops turnaround efforts.
Why do GameStop’s fair value estimates vary so widely?
The perceived fair value of GameStop shares shows a stark divergence among market participants. Opinions from the Simply Wall St Community, for example, span from US$30 to US$420.69. This wide gap highlights how far apart retail investors can be on the same ticker, even before recent insider buying and profitability updates. Analysts and investors grapple with weighing GameStop’s operational improvements against the company’s historical business challenges and the broader market’s long-term outlook for physical game retail. This range suggests considerable uncertainty regarding the sustainability of the current turnaround and the appropriate valuation for a company in transition.
Analyst Perspective & Market Impact
Analysts are now closely examining whether GameStop’s profitable quarter represents a repeatable model or a temporary reprieve. The $44.8 million net profit and $0.17 adjusted EPS are clear indicators of operational execution, particularly the strength in collectibles. Insider buying, especially from CEO Ryan Cohen, provides a tangible vote of confidence from leadership, which could help shift sentiment among some investors. However, the market remains divided on GameStop’s intrinsic value, with the core challenge being the long-term viability and scalability of its transformed business model amidst evolving consumer trends and intense e-commerce competition. Sustainable earnings growth and efficient capital allocation will be critical to bridging the current valuation gap.
Comparing GameStop’s Turnaround with Other Investment Theses
For investors contemplating GameStop’s future, it helps to compare its turnaround story with other types of investment plays focused on resilience, value, or growth. The challenges GameStop faces in transforming its business model highlight different risk and reward profiles.
| Investment Thesis | Core Strategy | Key Measure of Success | Primary Risk Factor |
|---|---|---|---|
| GameStop (GME) Turnaround | Transitioning from legacy retail, emphasizing cost control and collectibles growth. | Consistent positive EPS, scalable collectibles revenue, efficient inventory management. | Fragile consumer demand, heavy capital spending, e-commerce competition. |
| Solid Balance Sheet Plays | Focus on companies with robust financial health to withstand economic cycles. | Low debt-to-equity ratios, strong free cash flow, stable dividends. | Slower growth rates, market complacency, industry disruption. |
| Undervalued Quality Stocks | Identifying high-quality businesses trading below their intrinsic value. | Low valuation multiples (P/E, P/B) compared to peers, consistent earnings growth, competitive moat. | Value traps, sector-specific downturns, prolonged market apathy. |
Can GameStop translate its recent profitable quarter and reinforced insider conviction into a sustainable, scalable business model that justifies a significantly higher valuation amidst ongoing market skepticism?
Leave a Reply