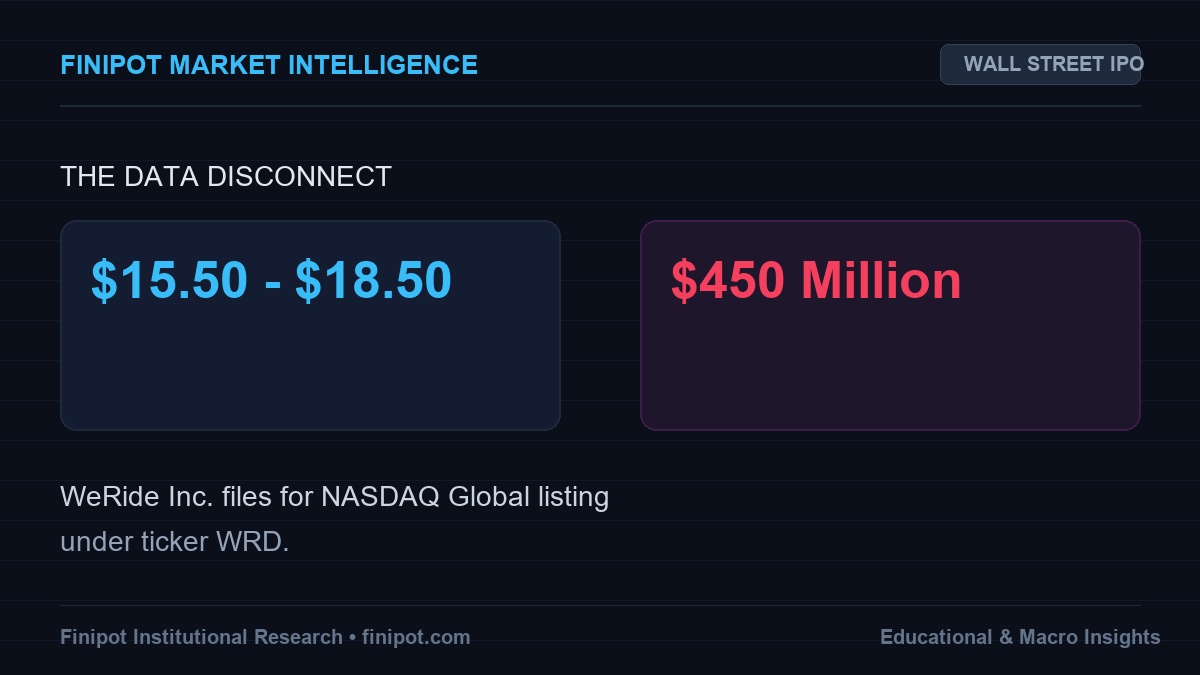
- Exchange & Ticker: NASDAQ Global (WRD)
- Price Range: $15.50 – $18.50
- Estimated Capital Raised: $450 Million
- Anticipated Listing Window: 2026-11-08
Business Model & Market Opportunity
WeRide Inc. is at the forefront of the autonomous vehicle revolution, specifically targeting the burgeoning robotaxi and robobus markets with its proprietary Level 4 autonomous driving technology. The company’s competitive moat is built upon extensive real-world operational experience, a robust technology stack, and strategic partnerships that facilitate rapid deployment. WeRide operates a multi-modal autonomous service, including passenger-focused robotaxis, public transport-oriented robobuses, and specialized autonomous street sweepers. This diversified approach allows them to tap into various segments of the urban mobility and logistics landscape. The addressable market is substantial and projected to grow exponentially as cities globally adopt smart transportation solutions, driven by efficiency gains, reduced emissions, and improved safety. WeRide’s strategy of phased deployment and scaling its operations across multiple cities positions it to capture a significant share of this evolving market.
Financial Profile & Capital Allocation
WeRide’s financial strategy centers on aggressive R&D investment to maintain its technological edge, coupled with a calculated expansion of its commercial service footprint. The $450 million in capital raised from this IPO is earmarked for several key initiatives: further development and refinement of its autonomous driving software and hardware, expansion of its robotaxi and robobus fleets, scaling operational infrastructure in existing and new markets, and potential strategic acquisitions or partnerships. While specific revenue figures and profitability timelines will be detailed in the S-1 filing, the company’s trajectory suggests a focus on revenue growth driven by service utilization and geographic expansion. The path to profitability will likely depend on achieving economies of scale, optimizing operational costs, and the widespread regulatory acceptance of autonomous mobility services.
Valuation Context & Peer Multiples
Evaluating WeRide’s valuation requires careful consideration of its unique position in a nascent but high-growth sector. As a pure-play autonomous driving technology and services provider with substantial operational deployment, WeRide presents a different profile than traditional automotive manufacturers or pure software companies. Comparison to listed peers in the autonomous vehicle space, including companies involved in ADAS technology, LiDAR, or autonomous trucking, will be crucial. Investors should look at metrics such as revenue multiples (once established), growth rates, market penetration, and projected future earnings. Given the capital-intensive nature of scaling autonomous fleets, valuation will heavily weigh the company’s ability to generate recurring revenue and achieve operational efficiency. Early-stage comparisons might involve a higher degree of speculative valuation until significant revenue streams and profitability are demonstrated.
Key Catalysts vs. Major Risk Factors
- Key Catalysts:
- 1. Accelerated Regulatory Approval: Favorable changes in global regulations for autonomous vehicle deployment could significantly expedite market penetration and service expansion.
- 2. Technological Milestones: Achieving further advancements in AI, sensor fusion, and predictive capabilities can enhance safety, reliability, and operational efficiency, strengthening competitive advantage.
- 3. Partnership Expansion: New strategic alliances with municipalities, logistics providers, and automotive manufacturers can unlock new revenue streams and accelerate growth.
- Major Risk Factors:
- 1. Regulatory Uncertainty: Evolving and fragmented regulatory landscapes across different jurisdictions pose a significant challenge to widespread commercial deployment.
- 2. Competition & Technological Obsolescence: The autonomous driving sector is highly competitive, with rapid technological advancements potentially rendering current solutions obsolete.
- 3. Public Perception & Safety Incidents: High-profile accidents or negative public perception regarding the safety of autonomous vehicles could lead to increased scrutiny and hinder adoption.
Analyst Takeaway: Buy, Wait, or Avoid?
For institutional investors, WeRide presents a compelling, albeit high-risk, high-reward opportunity in a transformative industry. The company’s proven operational deployment of Level 4 technology is a significant differentiator. However, the long-term path to profitability and the substantial capital required for scaling present considerable execution risks. A ‘Wait and See’ approach, focusing on post-IPO execution, revenue growth trajectory, and regulatory clarity, may be prudent for a more conservative assessment. Retail investors should carefully consider the speculative nature of early-stage autonomous vehicle companies, the volatility associated with growth stocks, and their personal risk tolerance before considering an investment.
Frequently Asked Questions
- What is the ticker symbol for WeRide Inc. on the NASDAQ Global? WeRide Inc. will trade under the ticker symbol WRD.
- What is the expected IPO price range for WeRide Inc.? The initial price band is set between $15.50 and $18.50 per share.
- When will the lock-up period for WeRide Inc. insiders expire? Specific lock-up period details will be available in the official S-1 filing; typically, these periods range from 90 to 180 days post-IPO.
Disclaimer: This analysis is for educational and informational purposes only and does not constitute financial advice or an offer to sell securities. Always read the official SEC prospectus / FCA filing before investing.
Leave a Reply